Key Takeaways
- Nvidia reports its first earnings since Huang’s exit
- Anthropic targets a record $1.4 trillion IPO
- Markets price an 88% chance of a December Fed hike
- Trump and Xi meet on trade and AI chips
Double Test for AI: Nvidia Without Huang, Anthropic at Nasdaq’s Door
Global markets will put the artificial intelligence trade to the test twice within three days this week, against a backdrop of tension and uncertainty. Central banks are closing out the year debating rate hikes rather than the cuts expected at the start of 2026. At the same time, rising bond yields are adding to the pressure on financial markets.
Nvidia Earnings: Strong Numbers May Not Be Enough
Nvidia will report results for the third quarter of fiscal 2027 after the US market close on Tuesday. The company has guided revenue of about $108 billion, with a gross margin of roughly 74%. Analysts expect around $109 billion.
Beyond the headline figures, forward guidance and any signal on a permanent successor will carry significant weight. Either could help calm the turmoil around the company after CEO Jensen Huang stepped down. The leadership shake-up has weighed heavily on the stock, which fell about 13% last week and now trades more than 30% below its level six weeks ago.
Anthropic IPO: The Biggest Listing in History?
Anthropic and some existing shareholders are seeking to raise more than $64 billion by selling 825 million shares at $70 to $78 each. That would value the company at up to $1.4 trillion. Trading is expected to begin on Nasdaq on November 19 under the ticker “ANT”, alongside a separate $26 billion private placement.
Analysts see the offering as a double-edged sword. A successful debut would confirm that investor appetite for AI remains intact. Yet raising nearly $90 billion could prompt some funds to trim their holdings in megacap tech stocks to free up cash, adding pressure on the Nasdaq.
Global Economic Outlook: What to Watch This Week
United States: Fed Rate Hike Bets Build
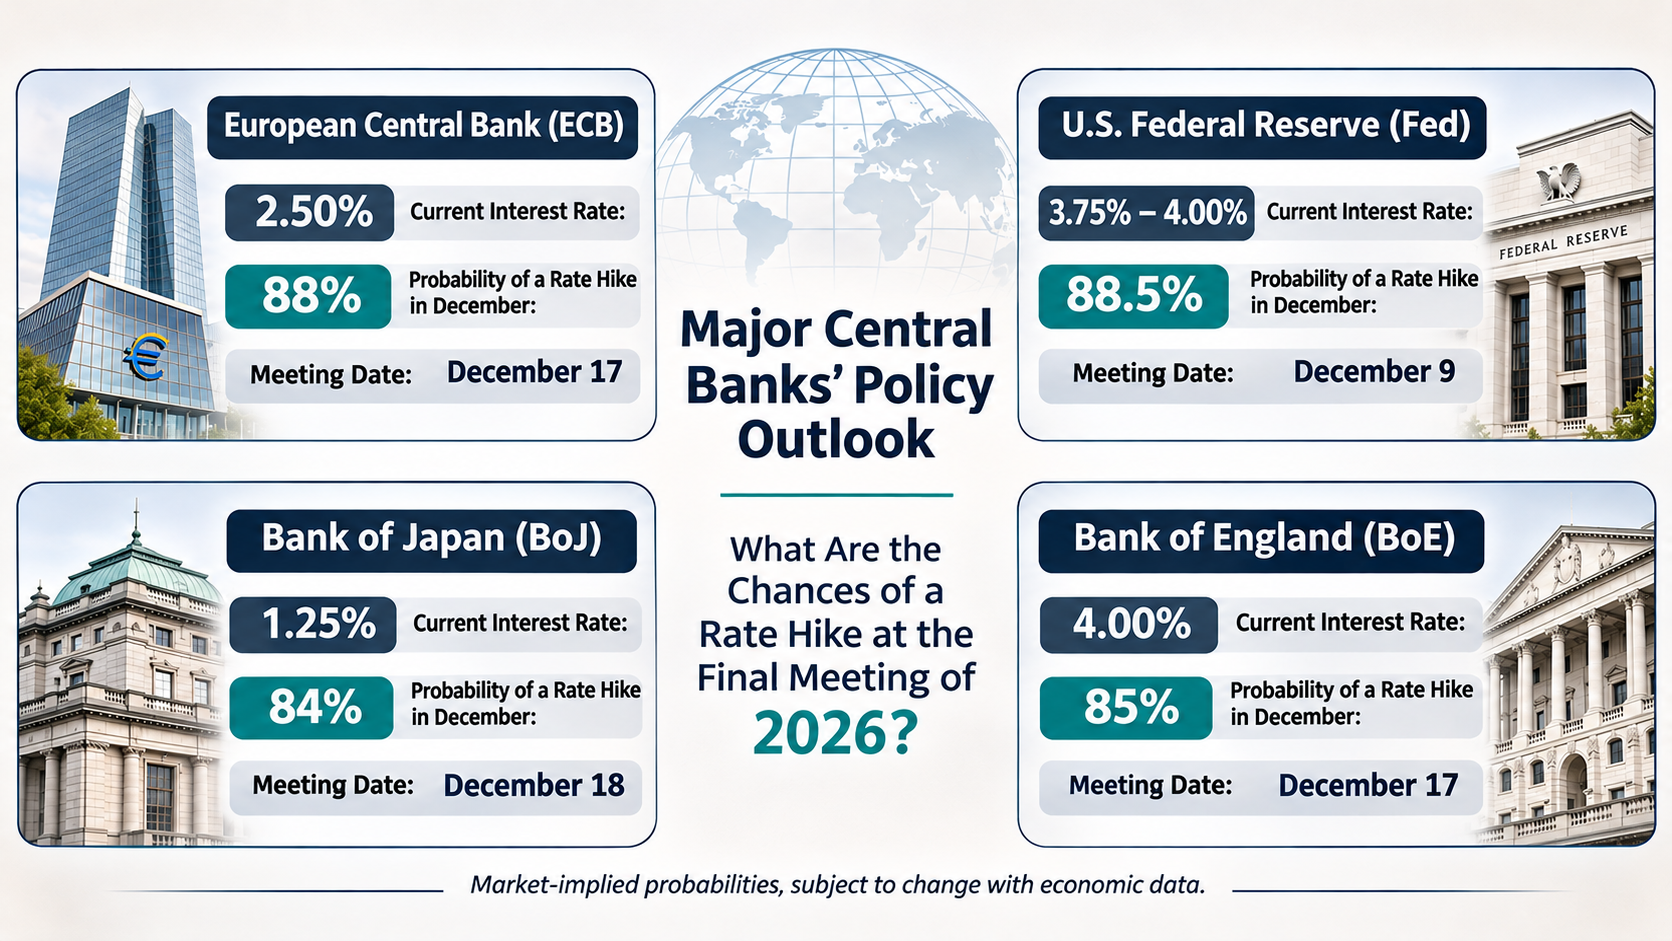
Markets are pricing an 88% probability of a Federal Reserve rate hike at the December meeting. Investors will look for further clues in the minutes of the October meeting. At that meeting, policymakers were divided over a hike before deciding to hold the federal funds rate at 3.75%–4.00%.
The data calendar is relatively light, with October retail sales in focus. Forecasts point to a marked slowdown, which would show how inflation is weighing on consumer demand.
Eurozone and UK: Inflation Sets the Pace
In the eurozone, final inflation figures and the ZEW survey are due. Reports suggest ECB policymakers are leaning toward a December rate hike followed by a pause.
In Britain, October inflation data are expected to show a slight rise, alongside fresh labour market figures. Markets assign an 85% probability to a Bank of England rate hike in December.
Japan and China: Yen Under Pressure, Beijing Under Scrutiny
Japan’s economy is expected to have grown 0.1% in the third quarter, down from 0.4% in the previous quarter. The slowdown complicates the policy picture, as markets still price an 84% probability of a Bank of Japan rate hike in December.
China will release its activity data, with industrial production and retail sales expected to slow. The central bank is expected to leave its benchmark lending rates unchanged at the end of the week.
Global markets will also watch the meeting between US President Donald Trump and Chinese President Xi Jinping in China on November 18–19. Trade, Taiwan and AI chip sales are on the agenda.